A Lasting Legacy

Guide to inheritance and estate planning in Ireland
Our 2025 guide to inheritance and estate planning contains the essential information you need to consider as part of a successful and impactful inheritance plan.
The key considerations are summarised in this interactive article and the full guide is available to download as a pdf using the form below.
CATRIONA COADY
Head of Tax, Goodbody
What is inheritance tax?
While tax should not be the sole consideration, understanding tax is an important point for gift and inheritance planning. Capital Acquisitions Tax (CAT) is the tax that is levied on gifts and/or inheritances.
Capital Acquisitions Tax is payable by the beneficiary of a gift or inheritance once they exceed the relevant tax-free CAT group threshold.
The current Capital Acquisitions Tax rate is: 33%
Capital Acquisitions Tax applies when the aggregate amount of all gifts and inheritances exceeds a certain threshold for the applicable Group.
Threshold
Relationship to giver
€400,000
Group A
A child of the person giving the gift or inheritance. Child includes an adopted child, stepchild, child of a civil partner and certain foster children.*
€40,000
Group B
A parent, brother, sister, niece, nephew, grandparent, grandchild, child of the civil partner of a brother or sister, lineal ancestor or a lineal descendant of the person giving the gift or inheritance.
€20,000
Group C
People with a relationship to the disponer not already covered in Groups A or B
Key Exemptions and Reliefs
In addition to the group thresholds, there are a number of important exemptions and reliefs to be aware of that can apply to either reduce the amount of Capital Acquisitions Tax due on a gift or inheritance.
The table below highlights some of the exemptions and reliefs you may be eligible for. However, specific conditions may apply to each exemption or relief. We recommend consulting the guide for full details.
The importance of dates
The date of a gift is generally the date it is received and the date of an inheritance is usually the date of death of the person leaving the inheritance.
The valuation date determines the date by which a CAT return must be filed, and the tax must be paid.
Effective planning is essential to ensure beneficiaries have enough time to meet tax payments, especially when the valuation date falls between January 1 and August 31.
Valuation dates |
Pay and File Dates |
| 1 January to 31 August | 31 October of the same year/extended ROS deadline |
| 1 September to 31 December | 31 October of the following year/extended ROS deadline |
The value of making a plan
Those who wish to plan for their estate and inheritance often don’t know where to start; they may be thinking about it but can find the conversation difficult. However, in our experience a review of all assets be they property and financial is a good place to start building a plan for the transfer of these assets. From a financial planning perspective, this is as simple as pulling together a list of assets and liabilities or “net worth”.
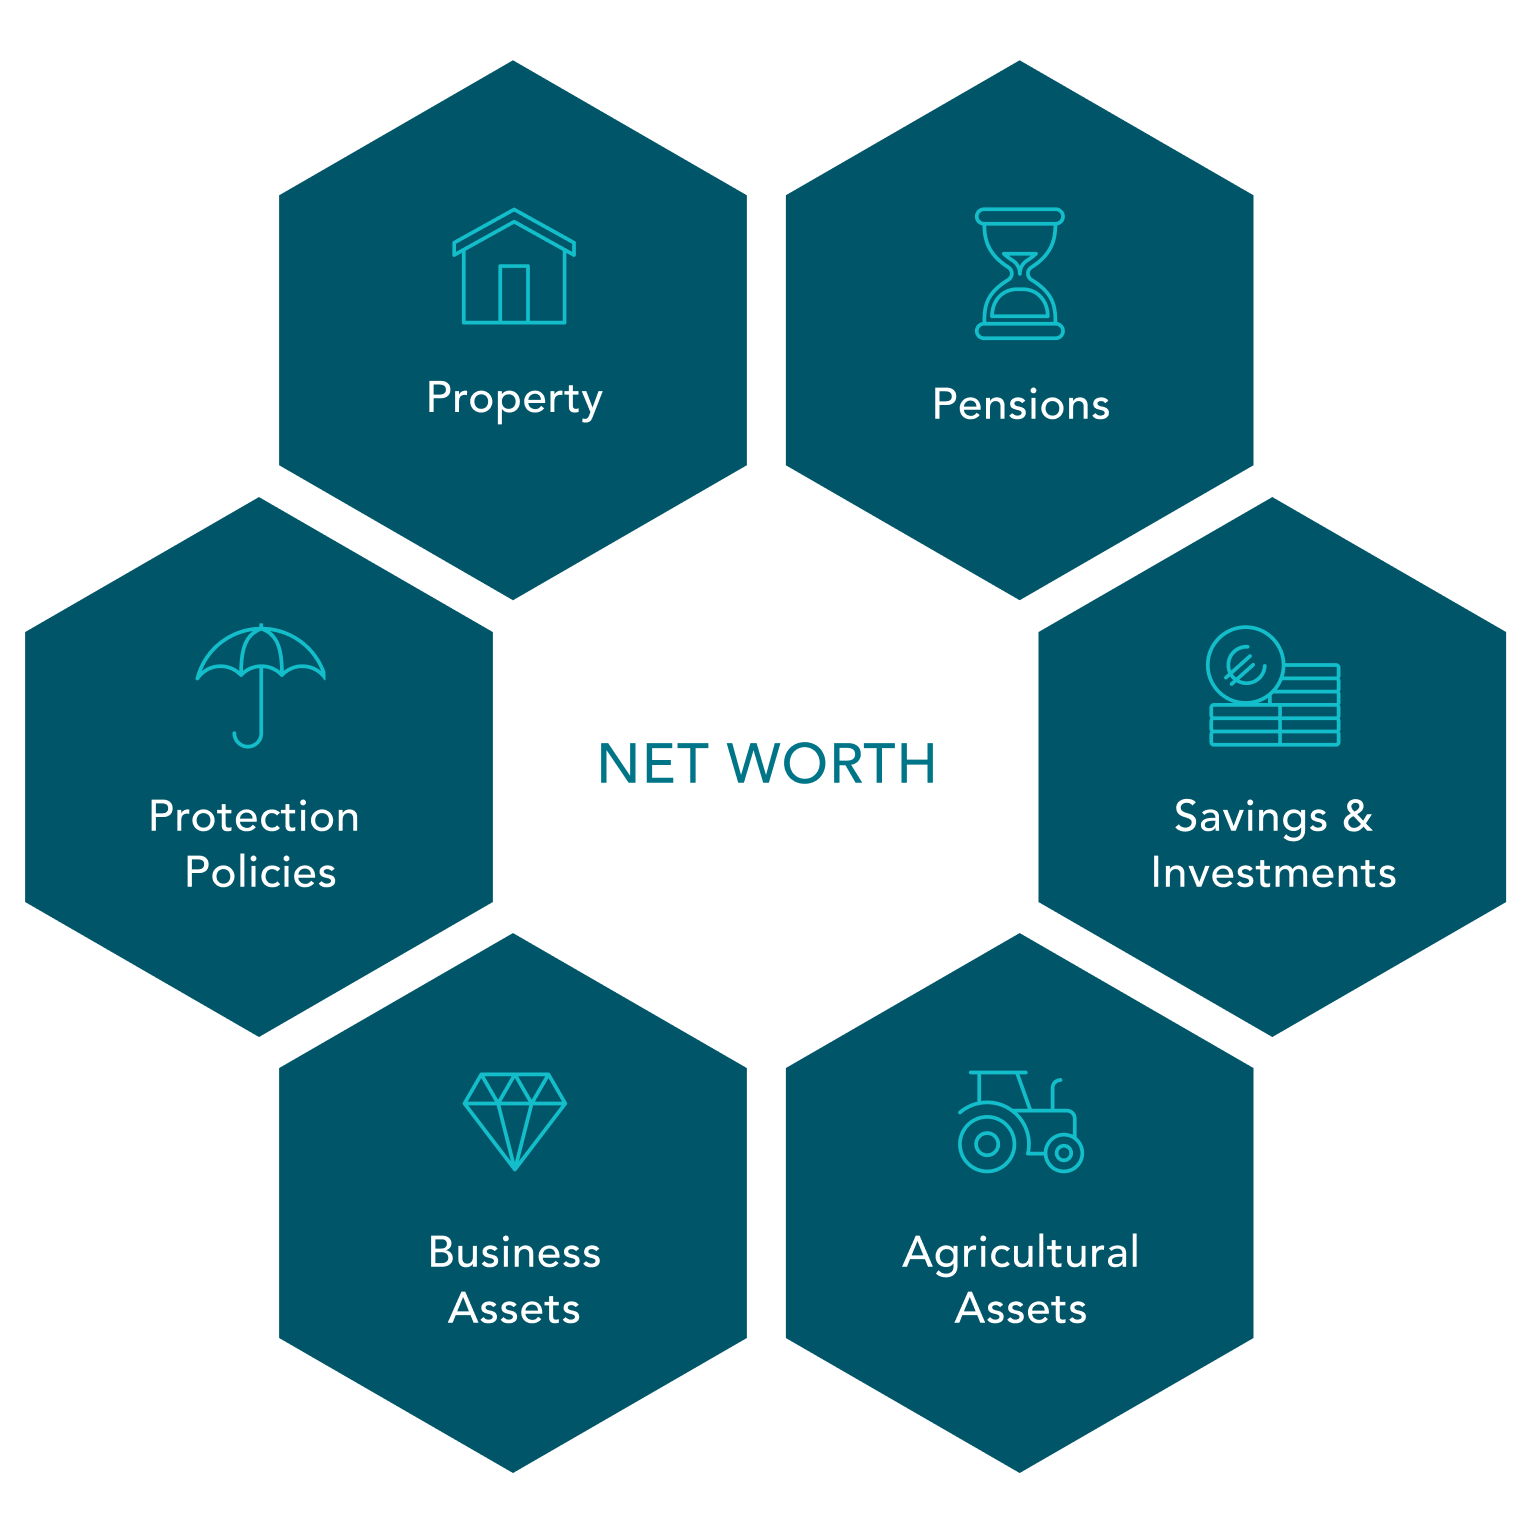
The 4 ‘Ps’ are key considerations when making an inheritance tax plan.
Structured Giving
There are a number of ways you can gift to children or grandchildren in a structured way. We recommend consulting the guide for full details.
Savings Fund
Bare Trusts for minor children
Involves parents gifting the value of the current CAT threshold or a portion of it to a child under 18. No CAT arises on this gift assuming that the threshold has not previously been utilised and that the threshold is not exceeded.
Family Partnerships
Limited and Unlimited
Where there is a concern about children having access to funds at age 18 and provided that there are sufficient funds or assets to warrant it, a family partnership can be formed to hold assets. This allows beneficial ownership of assets to pass to others (usually children) without control being passed.
Such partnerships are generally limited or unlimited.
Trusts
Trusts are a useful means of providing control or protection around a gift or ultimately an inheritance. Types of trust include:
- Bare trusts (outlined above)
- Life & limited interest trusts
- A discretionary trust
The Importance of Making a Will
A vital point to note:
One of the main reasons for making a will is that it provides a clear set of instructions for the transfer of property by means of a legal document.
Under the rules of intestacy, if this is not done the property is left to the State to divide the assets of the deceased.
As life circumstances change, existing wills should be updated in accordance with current circumstances and regardless of changing circumstances should be revisited every 3 to 5 years to be updated if necessary.
A will is valid once it:
- It is made in writing.
- The testator is over 18 years old.
- The testator has capacity to make a will.
- The testator signs or marks the will, at the end of the document, and acknowledges it in the presence of two witnesses.
- The testator’s two witnesses also sign the will in the presence of the testator.
- Neither of the testator’s witnesses – or their spouses or civil partners – receive anything in the will. Gifts to them will not be effective.
Enduring Power of Attorney (EPA)
An EPA is sometimes made at the same time as making a will and it is a legal document that can be set up by a person (a donor) to allow another person (an attorney), to look after their financial or personal affairs.
A donor can give the attorney the power to make decisions regarding their property and affairs, including the power to:
- Sell, exchange, mortgage or gift your property (subject to some limitations)
- Buy property on behalf of the donor
- Carry on a trade or profession on the donor’s behalf, where it is lawful to do so
- Carry out any contract the donor was a party to
- Pay debts, taxes and carry out any other duties